The United Arab Emirates has introduced a new credit-scoring system designed to provide a more comprehensive assessment of residents’ financial behaviour, repayment history and creditworthiness.
Etihad Credit Bureau has launched Credit Score 3i, an enhanced assessment model that replaces the previous methodology with a broader evaluation of individuals’ financial obligations. The new system extends the credit behaviour assessment period from 24 to 36 months and introduces two distinct scoring ranges to accommodate individuals with different levels of credit history.
The changes are expected to provide a more detailed picture of borrowers’ financial profiles while allowing eligible individuals with limited credit histories, including first-time borrowers and recent arrivals to the UAE, to receive a credit score.
The enhanced model also introduces provisions that could allow individuals who have settled previous defaults to see improvements in their credit scores within six months, provided they demonstrate responsible financial behaviour.
UAE Credit Score 3i: Understanding the Two Scoring Ranges
One of the most significant changes under Credit Score 3i is the introduction of two scoring ranges, designed to reflect the differences between established borrowers and individuals with limited credit histories.
- 300 to 850: Applicable to individuals with established credit histories.
- 300 to 650: Applicable to eligible individuals who are new to credit or new to the UAE and have limited credit histories.
Under the previous methodology, individuals with little or no borrowing history could face difficulties obtaining a meaningful credit assessment.
The new model addresses this limitation by allowing eligible individuals to receive a score based on the financial information available to the Bureau.
The separate scoring ranges are intended to provide a more appropriate assessment for different customer segments, helping lenders evaluate borrowers according to their respective credit histories.
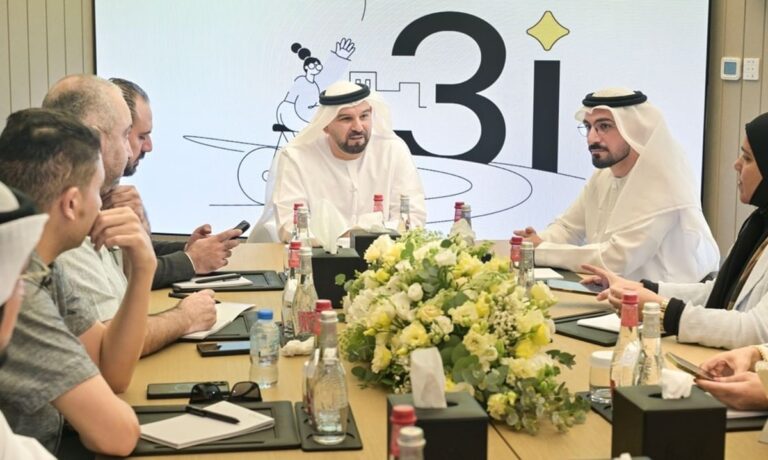
Marwan Ahmad Lutfi, Director General of Etihad Credit Bureau, said the enhanced model provides deeper insights into credit behaviour over longer periods while extending credit scoring to additional eligible segments.
The initiative is designed to improve the understanding of borrowers’ financial profiles and support more comprehensive credit risk assessments.
UAE Credit Checks Extended From 24 to 36 Months
Credit Score 3i introduces a longer assessment period, expanding the review of financial behaviour from 24 months to 36 months.
The extended timeframe allows the Bureau to examine a broader history of financial obligations, repayment patterns and changes in credit behaviour.
By analysing financial activity over three years, the system can provide a more comprehensive view of how individuals manage their credit commitments.
The additional information is expected to support authorised lenders, including banks, financial institutions and eligible fintech companies, in assessing borrowers’ financial risk.
However, the enhanced scoring model does not automatically determine whether an individual will receive a loan or credit facility.
Lenders remain responsible for making their own lending decisions, taking into account repayment capacity, existing obligations and other relevant financial information.
Can Your UAE Credit Score Improve After Settling a Default?
Credit Score 3i introduces an approach that recognises sustained improvements in financial behaviour, including the settlement of previous defaults.
According to Etihad Credit Bureau, individuals who have resolved previous defaults may see improvements in their credit scores within six months if they subsequently demonstrate consistent repayments and responsible management of their financial obligations.
The Bureau said the enhanced model analyses positive financial practices and recognises sustained improvements in credit behaviour.
However, a higher score within six months is not guaranteed.
The outcome depends on the individual’s overall credit profile, subsequent repayment behaviour and the scoring model’s assessment criteria.
New defaults, missed payments or other negative developments can affect an individual’s credit profile and delay potential improvements.
The system is intended to recognise positive financial behaviour over time rather than provide an automatic score increase following the settlement of a default.
Credit reports also provide information about the positive and negative factors influencing an individual’s score, alongside recommendations that may help improve their financial profile.
How to Check Your UAE Credit Score
Residents can access their credit scores and credit reports through Etihad Credit Bureau’s official digital channels.
The Bureau provides access through its website and mobile application, subject to registration and identity verification procedures.
- Official website: https://etihadbureau.ae/
- Mobile application: Etihad Credit Bureau, available through the Apple App Store and Google Play Store.
Residents are encouraged to review their credit information regularly and ensure that the details reflected in their reports are accurate.
Understanding the factors influencing a credit score can help individuals identify areas requiring attention, manage outstanding obligations and maintain a healthier financial profile.
Applicable service fees and access procedures are determined by the Bureau’s official channels.
UAE Credit Reports Expand to Include Buy Now, Pay Later Accounts
The launch of Credit Score 3i follows the expansion of Etihad Credit Bureau’s reporting coverage to include Buy Now, Pay Later (BNPL) accounts and other short-term credit products.
The inclusion of these financial commitments provides a broader view of individuals’ borrowing behaviour as digital credit services become increasingly common across the UAE.
The Bureau reported that its financial database covered approximately 11.6 million individuals and businesses as of September 2026.
Its database also contained 20.2 million active credit contracts and 25.3 million active International Bank Account Numbers (IBANs).
Demand for credit information has increased significantly over the past decade. The number of credit reports and scores issued annually rose from approximately one million in 2015 to more than 17 million in 2025.
The expansion reflects the growing importance of credit information in supporting financial institutions, borrowers and the wider UAE financial system.
What Credit Score 3i Means for UAE Residents
The introduction of Credit Score 3i represents a significant development in the UAE’s credit assessment framework.
By extending financial behaviour checks to 36 months, introducing separate scoring ranges and recognising sustained improvements after settled defaults, the system aims to provide a more detailed and inclusive assessment of creditworthiness.
For residents, the enhanced model offers an opportunity to better understand their financial profiles and the factors influencing their credit scores.
For lenders, it provides a broader set of information to support credit risk assessments and responsible lending decisions.
Ultimately, the system reinforces the importance of consistent repayments, responsible borrowing and effective management of financial obligations.
As the UAE’s financial sector continues to evolve, Credit Score 3i is designed to support a more comprehensive approach to credit assessment while encouraging stronger financial practices among individuals and businesses.