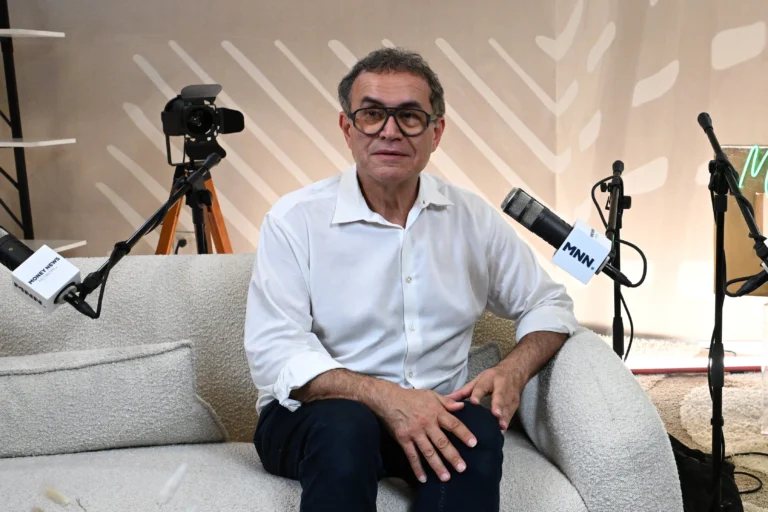
Economist Nouriel Roubini, widely known as “Dr Doom” for predicting the 2008 global financial crisis, believes the global economy is showing resilience despite recent trade and energy shocks. He now sees significant opportunities for long-term growth, driven by artificial intelligence (AI), technological innovation and reconstruction across parts of the Middle East.
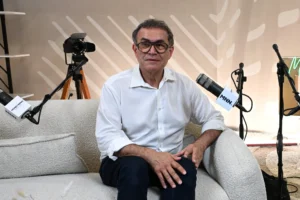
In an exclusive interview with Arabian Business on the sidelines of the SuperReturn conference in Dubai, Roubini identified Syria and Iraq as two countries with substantial potential for economic recovery and expansion as regional stability improves.
He also highlighted the UAE and the wider Gulf Cooperation Council (GCC) as increasingly important players in the global technology ecosystem, particularly through investments in AI infrastructure and related industries.
“I used to be Doctor Doom, now people call me Doctor Boom,” Roubini said, pointing to the global economy’s ability to absorb recent shocks and the powerful growth drivers emerging from next-generation technologies.
UAE and GCC Positioned to Benefit From the AI Revolution
Roubini said the economic impact of AI will extend well beyond software and the development of advanced language models. He expects the technology boom to create opportunities across a broad range of interconnected industries, including semiconductors, robotics, biotechnology, quantum computing, financial technology, renewable energy, defence technology and space exploration.
The UAE, he argued, is becoming an important participant in this wider transformation, alongside Asian economies that play significant roles in technology manufacturing and supply chains.
“It’s not just AI… in the supply chain of AI, Japan, South Korea, Taiwan, Malaysia, Thailand, India, this region of the world, the UAE, has been innovating in AI and life sciences,” he said.
Roubini also stressed that the AI expansion will require substantial investment in physical infrastructure. Energy, water and critical industrial metals will be essential to support increasingly resource-intensive computing systems and related industries.
This creates potential opportunities for countries with the capital, infrastructure and industrial capacity to support the next phase of technological development.
For the GCC, AI investment could therefore deliver benefits beyond digital services, extending into energy infrastructure, advanced manufacturing and other industries that underpin the technology economy.
Roubini Warns of AI Valuations but Sees Innovation Driving Growth
Despite his optimism, Roubini acknowledged that parts of the technology market could be overheating. Some companies developing frontier AI models remain unprofitable, and certain valuations may be vulnerable to corrections.
“Is there frothiness? Yes. Are some valuations maybe excessive? Could adjustment occur? Yes,” he said.
However, he argued that the broader technology transformation is supported by genuine innovation and commercial demand. He expects companies that successfully adopt new technologies to gain an advantage, while those that fail to adapt risk losing ground.
Roubini described this process as a form of creative destruction, in which some businesses thrive while others disappear as industries evolve.
He also distinguished the current technology boom from the dot-com bubble of the early 2000s. In his assessment, today’s largest technology companies have established substantial revenues, profits and business operations, unlike many internet companies that attracted investment during the earlier boom without sustainable commercial models.
Although individual businesses and private technology companies may fail, Roubini said he expects any broader market correction to be moderate rather than a threat to global economic stability.
Syria and Iraq Emerge as Potential Middle East Growth Markets
Beyond technology, Roubini identified Syria and Iraq as countries that could experience significant economic turnarounds if regional instability continues to ease.
He pointed to Syria’s human capital and historical economic importance, while highlighting the potential contribution of reconstruction investment from Gulf countries.
“The good news out of Syria is that now there is a new government committed to social and political stability,” Roubini said.
Reconstruction could create opportunities across infrastructure, housing, energy and other sectors while generating spillover benefits for neighbouring economies, including Lebanon. However, the scale and pace of any recovery will depend on political stability, financing and the ability to implement reconstruction projects.
Iraq, meanwhile, has substantial natural resources, particularly oil and energy, that could support future investment and economic development.
“Iraq went through turmoil but is a country that has a huge amount of natural resources, of course, oil and energy,” Roubini said.
For both countries, reduced instability could help unlock investment that has been constrained by years of conflict and uncertainty. Their longer-term prospects, however, will depend on whether improved conditions translate into sustained reconstruction, institutional stability and private-sector activity.
Roubini Prefers Gold Over Bitcoin as a Store of Value
On investment strategy, Roubini recommended geographic diversification across Asia, the Middle East and emerging markets, while expressing a preference for physical gold over cryptocurrencies as a store of value.
He cited gold’s performance relative to Bitcoin over the preceding year as part of his reasoning and argued that geopolitical and financial uncertainty could support a greater allocation to the precious metal.
“Given some of the economic, financial risks, geopolitical, probably some overweight in gold makes sense,” he said.
Roubini added that he preferred physical gold to Bitcoin, which he characterised as a highly volatile asset.
His comments reflect a cautious approach to cryptocurrencies at a time when investors are weighing geopolitical uncertainty, changing monetary conditions and the potential effects of technological disruption on financial markets.
US-China Competition Remains a Key Global Economic Risk
Roubini also addressed the strategic rivalry between the United States and China, arguing that the two economies could benefit from managed competition rather than treating their relationship as a zero-sum contest.
He pointed to the United States’ strengths in frontier AI and advanced chips, alongside China’s position in robotics, renewable energy and electric vehicles.
“If the US and China can form some kind of managed strategic competition, it’s going to be good for them, it’s also good for the world,” he said.
Cooperation or more predictable competition between the two economies could benefit other countries by supporting trade, investment and the adoption of new technologies. An escalation in tensions, by contrast, could disrupt supply chains and complicate the global economic outlook.
Roubini’s comments highlight the importance of international economic relationships as governments seek to secure strategic industries while maintaining access to global markets.
Trump’s Tariff Policies and Rising Debt Pose Economic Challenges
Roubini was critical of US President Donald Trump’s proposed tariff increases, arguing that the push to raise tariffs from around 3 per cent to 30 per cent risked triggering severe stagflationary pressures.
He said financial markets played an important role in constraining the administration’s approach, pointing to falling stock prices and rising bond yields as factors that encouraged a shift towards negotiated trade agreements.
“What forced him to blink, chicken out, was market discipline,” Roubini said.
He argued that market reactions can impose costs on governments pursuing policies that investors view as damaging, even when those governments have substantial economic influence.
Beyond trade, Roubini warned that rising public and private debt could become a growing concern as borrowing costs remain above the exceptionally low levels seen in previous years.
Large fiscal deficits and higher bond yields increase the cost of servicing government debt, potentially limiting the resources available for investment and public spending.
“We live in a world in which there are large stocks of private and public debt and, on the public side, large fiscal deficits and bond yields that used to be close to zero a few years ago now, depending on the country, are four, five percent or more,” he said.
He added that debt sustainability and the trajectory of borrowing costs would remain important considerations for investors and policymakers.
From Dr Doom to Dr Boom: Technology and Reconstruction Offer New Opportunities
Roubini’s outlook combines confidence in the growth potential of emerging technologies with caution over financial and geopolitical risks.
AI investment could create opportunities across the GCC and Asia, while reconstruction and improved stability could open new economic prospects for Syria and Iraq. At the same time, excessive technology valuations, trade disputes and rising debt remain potential sources of volatility.
For the Middle East, the opportunity will depend on translating investment and technological adoption into durable economic growth. Roubini’s assessment suggests that the region’s role in the next phase of global development could extend well beyond its traditional strengths in energy, particularly as the UAE expands its technology ambitions and reconstruction opportunities emerge in neighbouring markets.